You have been wearing glasses for years, your eye doctor says you are suitable for LASIK, and the procedure may cost tens of thousands of rupees. Since you already pay for health insurance every year, the obvious question is: will the insurer pay for it?
Laser eye surgery may be covered by health insurance in India, but routine LASIK or other refractive surgery done simply to get rid of glasses is often not covered. Coverage becomes more likely when the refractive error is severe, the procedure is medically necessary, or the vision problem has resulted from an accident, injury or another medical condition. The exact decision depends on your policy wording.
Why Is LASIK Often Not Covered?
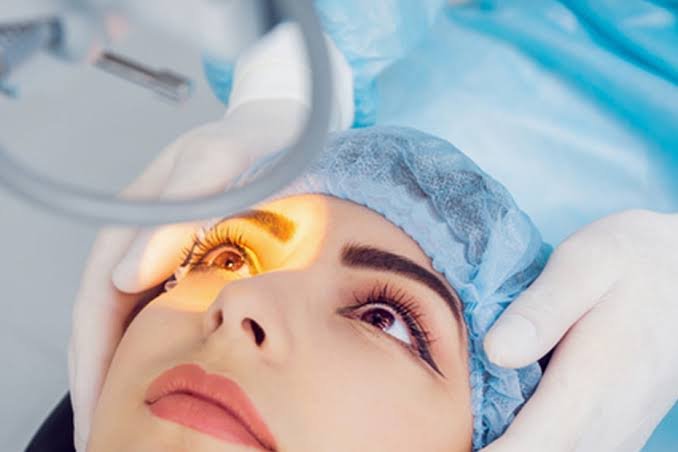
LASIK—Laser-Assisted In Situ Keratomileusis—is a refractive procedure used to correct vision problems such as myopia, hyperopia and astigmatism by reshaping the cornea.
For many people, however, the procedure is elective. They can still correct their vision using spectacles or contact lenses but choose laser surgery for convenience.
Health insurance primarily pays for eligible medical treatment required because of illness, disease or injury. Therefore, an insurer may not pay simply because a policyholder wants freedom from spectacles.
This is why a person with a relatively small refractive error who voluntarily undergoes LASIK should not assume that the health insurance policy will cover it.
The Important 7.5-Dioptre Rule
One of the most important numbers to understand when checking insurance coverage for refractive eye surgery is 7.5 dioptres.
Several health insurance policy wordings hosted by IRDAI contain a standard exclusion stating that expenses for correction of eyesight due to a refractive error of less than 7.5 dioptres are excluded.
That means a common situation looks like this:
Refractive error below 7.5 dioptres: Laser correction may be excluded under the policy.
Refractive error of 7.5 dioptres or more: The specific refractive-error exclusion may no longer apply, but this does not automatically guarantee that the entire surgery bill will be paid.
The claim must still satisfy the remaining conditions of the particular health policy.
Some insurers also explain that LASIK may receive coverage where the refractive error is severe—for example, above the specified 7.5-dioptre threshold.
So the safest approach is not to treat 7.5 dioptres as an automatic approval rule. Treat it as an important policy threshold that must be checked along with the rest of the coverage conditions.
When Can Laser Eye Surgery Be Covered?
There are situations where laser eye surgery has a much stronger medical justification.
Severe Refractive Error
If the patient’s refractive error meets the threshold specified by the health policy, refractive surgery may become eligible for coverage, subject to the policy’s other terms.
For example, someone with a very high power requiring medical correction is in a different situation from someone with mild myopia who simply prefers not to wear glasses.
Vision Problems Caused by an Accident
Suppose an accident damages the eye and corrective surgery becomes medically necessary.
Some health insurance policies may cover eye treatment arising from such an injury because the procedure is being performed as part of medical treatment rather than merely to eliminate the need for spectacles. Insurers themselves identify accident-related refractive problems as situations in which coverage may be available.
Refractive Error Following Another Surgery
A vision problem can sometimes develop or become significant following another surgical procedure. If laser correction is medically required as part of treatment, the insurer may consider the claim according to its policy conditions.
Inability to Use Glasses or Contact Lenses
There may also be unusual cases where a person cannot reasonably use conventional corrective options because of a physical condition, deformity or intolerance.
If an ophthalmologist establishes that surgery is medically necessary, the case may be considered differently from purely elective LASIK. Again, approval depends on the insurer and policy wording.
Do All Laser Eye Procedures Have the Same Insurance Rules?
No. “Laser eye surgery” is a broad expression. Procedures such as LASIK, PRK and SMILE can be performed to correct refractive errors, but lasers are also used in the treatment of other eye diseases.
That distinction matters.
For example, surgery required to treat a medical eye condition should not automatically be treated in the same way as elective laser vision correction.
Therefore, before asking the insurer, “Do you cover laser surgery?” ask a more precise question: “Does my policy cover this particular procedure for this particular diagnosis?”
That usually produces a much more useful answer.
What About Cataract Surgery?
Cataract surgery and LASIK should not be confused.
Cataract is an eye condition in which the natural lens becomes cloudy and interferes with vision. Treatment generally involves removing the affected lens and replacing it with an artificial intraocular lens.
LASIK, on the other hand, usually reshapes the cornea to correct refractive error.
Many health insurance policies provide cataract coverage subject to conditions, limits or waiting periods. The fact that modern technology or a laser is involved does not automatically make medically necessary eye treatment cosmetic.
So, if someone tells you, “Laser eye surgery is never covered by insurance,” that statement is too broad.
Check the Waiting Period Before Planning Surgery
Even where your procedure is covered, another issue can affect the claim: waiting periods.
A health policy may have an initial waiting period, a waiting period for specific diseases or procedures, or conditions relating to pre-existing diseases.
Suppose you already have a severe refractive error and purchase a new health insurance policy with the intention of undergoing surgery immediately. You should not assume the insurer will pay simply because your eye power crosses a particular threshold.
The effective coverage date and policy conditions still matter.
This is especially important for planned procedures because you have time to obtain written clarification from the insurer before undergoing surgery.
Cashless or Reimbursement: What Should You Check?
If the surgery is eligible, check whether your chosen eye hospital is part of the insurer’s network.
For a planned procedure, the hospital can normally send a pre-authorisation request for cashless treatment where the policy and network arrangement permit it.
If cashless treatment is unavailable, you may have to pay the hospital yourself and later apply for reimbursement, provided the claim is admissible.
Before surgery, ask the insurer or TPA for confirmation about:
- Whether the procedure is covered
- Applicable refractive-error limits
- Waiting periods
- Cashless availability
- Room or procedure limits, if any
- Deductibles or co-payments
- Documents required
- Any specific exclusion affecting refractive surgery
Getting this information beforehand can prevent an unpleasant surprise after the procedure.
Don’t Choose Surgery Based Only on Insurance
Insurance eligibility should not decide whether LASIK is medically right for you.
Laser vision correction is a medical procedure, and suitability depends on factors such as your refractive error, corneal condition, eye health and other clinical considerations. A qualified ophthalmologist should determine whether you are an appropriate candidate.
Insurance comes after that decision.
The better sequence is:
Medical suitability → Type of procedure → Insurance eligibility → Pre-authorisation → Surgery
Not the other way around.
The Bottom Line
Laser eye surgery can be covered by health insurance, but routine LASIK performed simply to reduce dependence on spectacles or contact lenses is often excluded.
One of the most important policy conditions is the refractive-error threshold. Many policy wordings exclude treatment for correction of eyesight where the refractive error is less than 7.5 dioptres.
However, crossing 7.5 dioptres should not be treated as automatic claim approval. Coverage still depends on your exact policy, medical necessity, waiting periods, exclusions and claim conditions.
If you are planning laser eye surgery, the most practical step is to send your doctor’s diagnosis and proposed procedure to the insurer before the surgery and obtain written confirmation about coverage.
FAQs
Q1. Does corporate health insurance cover LASIK surgery?
It may. Employer group health policies can have different benefits and exclusions from individual policies. Some employers may negotiate broader eye-care benefits. Check the group policy wording or ask the insurer/TPA before booking the surgery.
Q2. Can I claim insurance for LASIK on both eyes?
If LASIK itself is admissible under your policy, treatment of both eyes may be considered subject to the sum insured, procedure limits and other policy conditions. Eligibility of the procedure should be confirmed first.
Q3. Will insurance pay for pre-LASIK eye tests?
Not necessarily. Diagnostic tests may be payable when they form part of an admissible treatment claim and satisfy the policy conditions. If the LASIK procedure itself is excluded, routine pre-surgery tests may also remain outside coverage.
Q4. Should I get insurer approval before undergoing planned LASIK?
Yes, whenever possible. Ask the insurer or TPA for pre-authorisation or written clarification before a planned procedure. It can confirm whether your refractive error, diagnosis, hospital and proposed surgery satisfy the policy conditions and greatly reduce uncertainty about the claim.