Yes, physiotherapy can be covered by health insurance in India, but it is not automatically covered in every situation. Coverage is more common when physiotherapy is medically necessary and forms part of treatment following an eligible hospitalization. Routine outpatient physiotherapy without hospitalization may be covered only if your policy specifically includes OPD or physiotherapy benefits.
Therefore, the reason for physiotherapy, where you receive it and what your policy actually covers all matter.
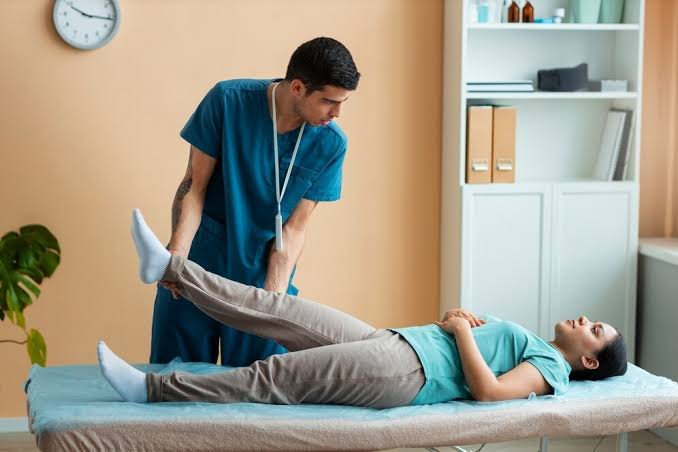
When Is Physiotherapy Usually Covered?
One of the most common situations is physiotherapy prescribed after hospitalization.
Suppose you undergo:
- Knee replacement surgery
- Hip replacement surgery
- Spine surgery
- Treatment for a serious fracture
- Surgery after an accident
- Treatment following a stroke
After discharge, your doctor may recommend physiotherapy to restore movement, strength and normal functioning.
If your health insurance policy covers post-hospitalization medical expenses and the physiotherapy is directly connected with an admissible hospitalization, those expenses may be reimbursable according to the policy conditions.
HDFC ERGO, for example, states that physiotherapy can be reimbursed under post-hospitalization cover when it has been prescribed by a doctor after hospital admission.
This is quite different from visiting a physiotherapist independently for occasional back or neck pain.
What Is Post-Hospitalization Physiotherapy?
Most comprehensive health insurance policies provide a defined period of coverage for eligible medical expenses incurred after discharge from hospital.
The exact number of days varies from policy to policy.
Imagine you are hospitalized following a road accident and undergo surgery for a leg fracture. After discharge, the orthopaedic surgeon prescribes 20 physiotherapy sessions.
If the hospitalization claim itself is accepted and the physiotherapy falls within the policy’s post-hospitalization period and other conditions, the treatment may qualify for reimbursement.
HDFC ERGO specifically lists physiotherapy as an example of treatment that can be necessary after hospital discharge and potentially covered under post-hospitalization benefits.
The important connection is:
Hospitalization → Doctor’s prescription → Related physiotherapy
The stronger that connection is, the clearer the insurance claim usually becomes.
What About Physiotherapy Without Hospitalization?
This is where many claims become uncertain.
Suppose you develop chronic shoulder pain and your doctor recommends ten physiotherapy sessions, but you are never admitted to hospital.
A traditional hospitalization-focused health insurance policy may not cover those sessions because they are being taken purely on an outpatient basis.
However, some policies and add-ons specifically provide OPD physiotherapy benefits.
ICICI Lombard’s BeFit Cover, for example, specifically includes physiotherapy sessions as an outpatient benefit along with consultations, pharmacy and diagnostic services.
Therefore:
Post-hospitalization physiotherapy: Often potentially covered under regular health insurance.
Standalone OPD physiotherapy: Usually requires a policy or add-on that specifically covers it.
Never assume the two are treated the same way.
Can a Policy Have a Separate Physiotherapy Limit?
Yes.
Even when physiotherapy is covered, the insurer may place a separate limit on the benefit.
An older policy wording hosted on IRDAI’s website provides a good example. The policy specifically covered outpatient physiotherapy but restricted it to the amount stated in the policy schedule, required treatment to be prescribed by a specialist, and limited the number of physiotherapy sittings per illness or injury.
This shows why a ₹10 lakh health insurance policy does not necessarily mean you have ₹10 lakh available for physiotherapy.
Your policy could instead provide something such as:
Overall health cover: ₹10 lakh
Physiotherapy benefit: Separate specified limit
Always check for:
- Session limits
- Annual limits
- Per-illness limits
- Waiting periods
- Network restrictions
These conditions can make a major difference when long-term rehabilitation is required.
Is a Doctor’s Prescription Necessary?
In many cases, yes.
Insurance generally treats physiotherapy more favourably when it is medically necessary and prescribed as part of treatment for an illness or injury.
The policy wording mentioned above, for example, required physiotherapy to be prescribed by a specialist for specified medical conditions.
Therefore, simply joining a physiotherapy centre because you experience general stiffness or want better mobility may not qualify.
For a claim, preserve:
- Doctor’s prescription
- Diagnosis
- Hospital discharge summary
- Physiotherapy advice
- Session bills
- Payment receipts
- Treatment records
These documents help establish that the physiotherapy was part of genuine medical treatment.
Is Physiotherapy After an Accident Covered?
It can be.
Suppose you suffer a shoulder or leg injury in an accident and require hospitalization followed by rehabilitation.
If the accident-related hospitalization is covered and physiotherapy is prescribed as part of recovery, the subsequent treatment may fall under post-hospitalization coverage, subject to the policy conditions.
Some policies may also provide a specific physiotherapy benefit independent of hospitalization.
The key point is that accident-related physiotherapy is not automatically payable merely because an accident occurred. The treatment must still satisfy the insurance policy’s requirements.
What About Physiotherapy for Back Pain?
Back pain is one of the most common reasons people visit physiotherapists, but insurance coverage depends heavily on the circumstances.
Consider two situations.
Situation 1: You undergo spine surgery and require physiotherapy after discharge.
This may qualify as post-hospitalization treatment.
Situation 2: You experience recurring lower-back pain from sitting at a desk and independently attend physiotherapy sessions.
Those sessions may not be covered under a regular hospitalization policy unless OPD physiotherapy is specifically included.
Therefore, the medical condition alone does not determine coverage.
How the treatment fits into your policy is equally important.
Is Home Physiotherapy Covered?
Not automatically.
Many people recovering from major surgery, stroke or mobility problems prefer a physiotherapist to visit their home.
Whether these sessions are covered depends on the policy’s wording.
A policy may require physiotherapy to take place at a recognized hospital, clinic or network provider. Some products may permit home-based treatment under specific domiciliary or rehabilitation benefits.
Therefore, before arranging several weeks of home physiotherapy, ask the insurer:
“Are physiotherapy sessions at home admissible under my policy?”
Get written confirmation whenever possible.
Cashless or Reimbursement?
Physiotherapy claims can work differently depending on the policy.
If physiotherapy is part of an insurer’s cashless OPD network, the policyholder may be able to receive covered treatment without paying the entire cost upfront. ICICI Lombard’s BeFit benefit, for example, operates as a cashless OPD cover and includes physiotherapy.
For post-hospitalization physiotherapy, reimbursement is also common. You may have to pay for the sessions and later submit the bills along with the medical documents.
Check the process before treatment begins, especially if dozens of sessions are planned.
Physiotherapy and Health Insurance: The Common Mistakes
One mistake is assuming that every medically recommended treatment is automatically covered by health insurance.
Another is assuming that OPD and post-hospitalization physiotherapy are identical.
They are not.
People also sometimes begin treatment at a local physiotherapy centre and collect handwritten bills without checking whether the provider meets the insurer’s requirements.
Finally, some policyholders discover too late that their physiotherapy benefit has a limited number of sessions or a separate monetary cap.
A five-minute call to the insurer before beginning treatment can prevent many of these problems.
What Should You Check Before Starting Physiotherapy?
Ask your insurer or TPA:
- Is physiotherapy covered under my policy?
- Does hospitalization have to occur first?
- How many post-hospitalization days are covered?
- Do I need a specialist’s prescription?
- Is there a maximum number of sessions?
- Is there a separate physiotherapy sub-limit?
- Can I take treatment at home?
- Does the physiotherapy centre need to be in the insurer’s network?
- Can the treatment be cashless, or will I need reimbursement?
The answers should come from your actual policy wording rather than from general assumptions about health insurance.
The Bottom Line
Yes, physiotherapy can be covered by health insurance, but coverage depends on why and how the treatment is being taken.
Physiotherapy prescribed after an eligible hospitalization is more likely to fall under post-hospitalization benefits. HDFC ERGO, for example, specifically states that doctor-prescribed post-hospitalization physiotherapy can be reimbursed where the policy provides that benefit.
Routine outpatient physiotherapy without hospitalization is less likely to be covered under a standard policy unless there is a specific OPD or physiotherapy benefit. Some modern add-ons, such as ICICI Lombard’s BeFit Cover, expressly include physiotherapy sessions.
Therefore, before beginning a long course of treatment, check the prescription requirement, number of sessions, sub-limit, provider restrictions and whether treatment must be connected to hospitalization.
FAQs
Q1. Is physiotherapy after knee replacement covered by health insurance?
It may be covered when prescribed by the treating doctor as part of recovery following an admissible knee-replacement hospitalization and when the policy includes post-hospitalization expenses. The treatment must also fall within the policy’s applicable time and benefit limits.
Q2. Does health insurance cover physiotherapy for sports injuries?
It can, particularly when the sports injury requires covered medical treatment or hospitalization followed by prescribed physiotherapy. Pure outpatient treatment may require specific OPD or physiotherapy coverage.
Q3. Can senior citizens claim physiotherapy expenses?
Yes, if their health insurance policy provides physiotherapy coverage and the treatment satisfies its conditions. Age alone does not determine whether physiotherapy is payable. The reason for treatment, prescription, waiting periods and benefit limits remain important.
Q4. Will insurance cover physiotherapy sessions for several months?
Possibly, but not without limits. Policies can restrict the number of sessions, total payable amount or period during which post-hospitalization expenses are covered. A policy wording hosted by IRDAI, for example, demonstrates how physiotherapy benefits may carry both session and monetary limits.