The market opens, hundreds of share prices begin moving, and two fund managers start the day very differently. One follows a ready-made index and adjusts the portfolio only when that index changes. The other studies companies, meets management teams and buys stocks that may perform better than the market.
These two approaches represent index funds and active equity funds. Index funds aim to follow the market at a low cost, while active funds try to outperform it through professional stock selection.
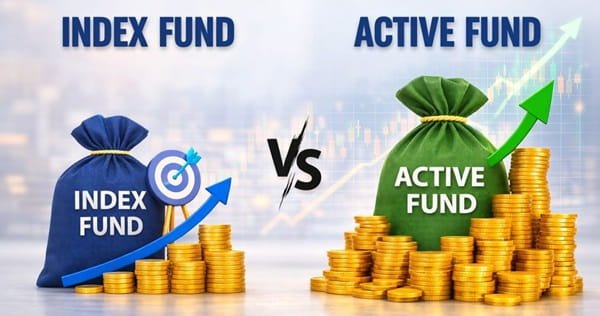
Neither option is automatically better. The right choice depends on cost, investment knowledge, risk tolerance and confidence in a fund manager’s ability to deliver better returns consistently.
What Is an Index Fund?
An index fund is a passively managed mutual fund that tries to replicate the performance of a particular market index, such as the Nifty 50, Nifty Next 50 or Sensex.
Instead of selecting companies independently, the fund invests in the securities included in its chosen index, generally in similar proportions. Under SEBI’s current categorisation framework, index funds and exchange-traded funds must invest at least 95% of their total assets in securities belonging to the index they track.
The objective is not to defeat the index. It is to deliver returns close to the index after accounting for expenses and operational differences.
What Is an Active Equity Fund?
An active equity fund is managed by a professional fund manager who decides which shares to buy, hold or sell.
The manager may study a company’s earnings, management quality, debt, competitive position, valuation and growth prospects. The portfolio can differ considerably from its benchmark because the fund aims to generate additional returns, commonly called alpha.
“Active equity fund” is a broad description rather than one official SEBI category. Large cap, flexi cap, mid cap, small cap, focused and value funds may all follow active investment strategies. AMFI distinguishes active funds by their reliance on fund-manager decisions and their aim of outperforming a benchmark.
Index Fund vs Active Equity Fund: Major Differences
1. Investment Strategy
An index fund follows a predetermined index. The fund manager does not choose companies based on personal expectations about their future performance.
An active fund gives the manager freedom to select companies, avoid unattractive stocks and change portfolio allocations according to research and market conditions.
The index approach is rule-based, while active investing depends more heavily on human judgement.
2. Investment Objective
The main goal of an index fund is to match the performance of its benchmark as closely as possible.
An active equity fund aims to outperform its benchmark after accounting for costs. However, outperformance is not guaranteed. A fund can remain behind its benchmark for several years, even when it has an experienced manager.
Investors should compare active funds with the correct benchmark rather than looking only at their absolute returns.
3. Cost
Index funds generally have lower expense ratios because they require less research, stock selection and portfolio trading. SEBI’s investor guidance also identifies lower management costs as a major feature of index investing.
Active funds normally charge higher expenses because they need research teams, fund managers and more frequent portfolio decisions.
Even a small difference in annual costs can affect long-term wealth through compounding. An active fund must generate enough additional return to cover its higher expenses before it creates a real advantage for investors.
4. Fund Manager Risk
An index fund has limited fund-manager risk because the manager primarily follows the composition of the selected index.
An active fund is more dependent on the manager’s decisions. Good stock selection can produce superior returns, but mistakes involving companies, sectors or valuations can result in underperformance.
A change in the fund manager or investment process can also affect an active scheme’s future behaviour.
5. Tracking Error
Index funds carry tracking error, which is the difference between the return of the fund and the return of its benchmark.
This difference can arise because of expenses, cash holdings, delays in portfolio rebalancing and transaction costs. A lower tracking error generally indicates that the fund is following its index more efficiently.
Tracking error is not normally the main concern in an active fund because its portfolio is intentionally different from the benchmark.
6. Return Potential
An index fund will usually rise and fall with its chosen index. It cannot avoid an overvalued or poorly performing company while that company remains part of the benchmark.
An active fund may reduce exposure to weak companies and invest more in promising opportunities. This creates the possibility of outperforming the index.
However, the same freedom can work against investors. Incorrect stock selection or unsuccessful market calls may cause the fund to deliver lower returns than a simple index fund.
7. Portfolio Transparency
Index fund portfolios are comparatively predictable because the underlying index and its constituents are publicly known.
Active fund portfolios can change according to the manager’s decisions. Investors receive regular portfolio disclosures, but they cannot predict every future change.
People who prefer a simple and easily understood portfolio may find an index fund more comfortable.
8. Diversification
A broad-market index fund may provide exposure to several companies and sectors through one investment. This reduces dependence on the performance of a single stock.
However, every index is not equally diversified. Sectoral, thematic and strategy-based indices can remain highly concentrated.
An active fund’s diversification depends on its category and investment style. A flexi cap fund may spread money widely, while a focused fund can hold a limited number of stocks.
Who Should Choose an Index Fund?
An index fund may be suitable for investors who:
- Want a simple, low-cost equity investment
- Do not want to select and monitor fund managers
- Are satisfied with market-linked returns
- Prefer a transparent investment strategy
- Have an investment horizon of at least five to seven years
- Want a core holding for their equity portfolio
Index funds can be particularly useful for beginners who want broad market exposure without regularly comparing active schemes.
Who Should Choose an Active Equity Fund?
An active equity fund may suit investors who:
- Want the possibility of outperforming the benchmark
- Trust professional research and stock selection
- Can tolerate periods of underperformance
- Are willing to pay a higher expense ratio
- Can evaluate the fund’s strategy and manager
- Want exposure to opportunities not adequately represented in an index
Active funds may be more useful in market segments where research and stock selection can play a greater role. However, investors should not choose them only because of one or two years of strong returns.
Can You Invest in Both?
Yes. Index and active funds can complement each other.
An index fund may form the low-cost core of the portfolio, while a carefully selected active fund can provide the possibility of additional returns.
For example, an investor may use a broad large cap index fund for core exposure and an active flexi cap or mid cap fund for differentiated stock selection.
Before combining schemes, check their major holdings. A large cap active fund may own many of the same companies as a large cap index, creating considerable overlap.
Index Fund or Active Equity Fund: Which Is Better?
An index fund is generally better for investors who value low costs, simplicity, transparency and returns close to the broader market.
An active equity fund may be better for investors seeking benchmark-beating potential and who are confident in selecting and monitoring a capable manager.
For beginners, a broad index fund can provide a practical starting point. Experienced investors may combine passive and active strategies rather than depending entirely on one approach.
The better fund is not simply the one with the highest past return. It is the one whose strategy, cost and risk allow you to remain invested consistently.
Frequently Asked Questions
1. Can an index fund outperform its benchmark?
It generally aims to match the benchmark, not outperform it. After expenses and tracking differences, its return is usually slightly lower than that of the index.
2. What happens when a company is removed from an index?
The index fund adjusts its portfolio according to the revised index. It generally sells the removed company and purchases the newly included stock in the required proportion.
3. Is a low expense ratio enough to select an index fund?
No. Investors should also compare tracking error, tracking difference, fund size, portfolio replication method and the suitability of the underlying index.
4. Should an active fund be changed after one year of underperformance?
Not necessarily. One year is too short to judge many equity strategies. Compare performance across a complete market cycle and examine whether the manager, process or portfolio quality has materially changed.
5. Is an index fund protected from market crashes?
No. An index fund follows its benchmark downward as well as upward. Diversification can reduce company-specific risk, but it cannot prevent losses during a broad market correction.
Bottom Line
Index funds follow a rule-based, low-cost approach and aim to deliver returns close to a selected benchmark. Active equity funds rely on professional decisions and attempt to perform better than that benchmark.
Choose an index fund when simplicity, low expenses and market-level performance are enough. Choose an active equity fund when you accept higher costs and manager risk in return for the possibility of outperformance.
For many investors, a low-cost index core combined with limited active exposure can provide a sensible balance.