Buying a home is one of the largest financial commitments many people make. Before purchasing a property, prospective homeowners need to understand not only the property’s price but also how much they may have to pay every month toward the loan. A mortgage loan calculator can provide a quick estimate of this monthly housing payment.
In India, home financing is commonly structured as a housing loan with monthly Equated Monthly Instalments (EMIs). A mortgage loan calculator generally uses the loan amount, interest rate and repayment tenure to estimate the EMI. Some advanced calculators may also account for down payment, processing fees, property-related expenses and other assumptions.
Understanding how these calculations work helps borrowers compare loan options and assess affordability before making a long-term financial commitment.
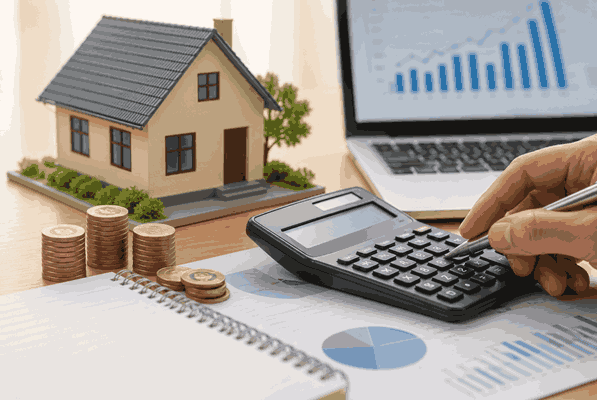
What Is a Mortgage Loan Calculator?
A mortgage loan calculator is an online financial tool that estimates the monthly repayment associated with a home loan.
The basic calculator usually requires three important inputs:
- Loan amount
- Interest rate
- Loan tenure
For example, a borrower considering a ₹40 lakh home loan at a particular interest rate can enter the amount and compare different repayment periods.
The calculator then estimates the EMI and, depending on its features, may also show the total interest and total repayment over the loan’s tenure.
How Mortgage Calculators Calculate EMI
For a standard reducing-balance loan, the EMI is commonly calculated using:
EMI = P × R × (1 + R)ⁿ ÷ [(1 + R)ⁿ − 1]
Where:
- P = Principal or loan amount
- R = Monthly interest rate
- n = Total number of monthly instalments
Because lenders usually quote interest rates annually, the annual rate is converted into a monthly rate for this calculation.
For example, an annual interest rate of 8% corresponds to an illustrative monthly rate of:
8% ÷ 12 = 0.6667%
If the repayment period is 20 years:
20 × 12 = 240 monthly instalments
The calculator applies these figures to estimate the monthly EMI.
Example of a Mortgage EMI Calculation
Suppose a homebuyer takes a ₹40 lakh loan at an assumed interest rate of 8% per year for 20 years.
The inputs are:
- Loan amount = ₹40,00,000
- Annual interest rate = 8%
- Monthly interest rate = approximately 0.6667%
- Tenure = 240 months
Using the standard EMI formula, the estimated monthly payment is approximately ₹33,458.
The estimated total repayment would be approximately:
₹33,458 × 240 = ₹80.30 lakh
This means the approximate interest component would be:
₹80.30 lakh − ₹40 lakh = ₹40.30 lakh
These figures are illustrative and rounded. The actual EMI can differ depending on the lender’s interest rate, calculation methodology, disbursement schedule and loan terms.
How Interest and Principal Are Distributed
A home-loan EMI generally consists of both principal and interest.
During the early stages of repayment, the outstanding loan balance is relatively high. Consequently, the interest component can account for a significant portion of the EMI.
For the ₹40 lakh example, the first month’s interest at 8% annual interest would be approximately:
₹40,00,000 × 0.6667% ≈ ₹26,667
If the EMI is approximately ₹33,458, the remaining amount of roughly:
₹33,458 − ₹26,667 = ₹6,791
would initially go toward reducing the principal.
As the outstanding balance decreases, the interest calculated on that balance generally decreases. Therefore, a larger portion of subsequent EMIs goes toward principal repayment, assuming the interest rate remains unchanged.
This repayment pattern is reflected in an amortisation schedule.
How Loan Tenure Changes Monthly Housing Payments
Tenure is one of the most important inputs in a mortgage calculator.
Using the same ₹40 lakh loan at an assumed 8% annual interest rate:
| Tenure | Approx. Monthly EMI | Approx. Total Interest |
| 10 years | ₹48,532 | ₹18.24 lakh |
| 20 years | ₹33,458 | ₹40.30 lakh |
| 25 years | ₹30,857 | ₹52.57 lakh |
These figures are illustrative.
A longer tenure reduces the monthly EMI because repayment is spread across more instalments. However, the total interest can increase substantially.
This is why borrowers should evaluate both monthly affordability and total borrowing cost rather than choosing a loan solely because it has a lower EMI.
Role of Down Payment
A mortgage calculator can also help borrowers understand how the down payment affects financing.
Suppose a property costs ₹50 lakh and the buyer contributes ₹10 lakh from personal funds. If the remaining ₹40 lakh is financed, the calculator would use ₹40 lakh as the loan principal.
A larger down payment can reduce the amount borrowed and, consequently, the EMI and total interest, subject to the lender’s applicable financing terms.
However, buyers should also account for other upfront expenses instead of using all available savings for the down payment.
Are EMI and Monthly Housing Costs the Same?
Not necessarily.
A basic mortgage calculator generally estimates the loan EMI, not every expense associated with owning a home.
The overall monthly housing budget may also include expenses such as:
- Maintenance charges
- Society or association charges
- Property taxes
- Insurance, where applicable
- Utilities
- Repairs and maintenance
- Parking or other property-specific expenses
Some international mortgage calculators may include property taxes, homeowner’s insurance and similar costs in their monthly estimate. Indian home-loan calculators may focus primarily on EMI.
Therefore, borrowers should check exactly what a particular calculator includes.
Effect of Floating Interest Rates
Many housing loans may use interest rates that can change according to the applicable lending structure.
If the interest rate changes, the future repayment schedule may also change. Depending on the lender’s terms, the change may affect the EMI, loan tenure or both.
For this reason, an EMI calculated using today’s rate should not automatically be assumed to remain unchanged for the entire loan period.
Borrowers should review the loan agreement and understand how interest-rate changes are handled.
Additional Costs Not Included in Basic Calculators
The total cost of purchasing a home extends beyond the loan principal and interest.
Depending on the transaction and location, buyers may need to consider:
- Stamp duty
- Registration charges
- Processing fees
- Legal and documentation expenses
- Brokerage, where applicable
- Property valuation charges
- Interior or renovation expenses
These costs may not be included in a basic mortgage calculator.
Consequently, buyers should prepare a separate property-purchase budget in addition to calculating the EMI.
How Prepayment Can Affect Housing Costs
Homebuyers may make partial prepayments when they have additional funds available.
Reducing the outstanding principal can reduce the amount on which future interest is calculated under a reducing-balance structure. Depending on the lender’s terms, a prepayment may reduce the remaining tenure, EMI or both.
Before making a prepayment, borrowers should review the applicable loan conditions and any charges.
Conclusion
Mortgage loan calculators estimate monthly housing payments primarily by using the loan amount, interest rate and repayment tenure. For a standard reducing-balance loan, the calculator applies an EMI formula and can show the estimated monthly payment, total interest and overall repayment.
A longer tenure can reduce the monthly EMI but generally increases the total interest cost. A larger down payment can reduce the amount borrowed, while changes in floating interest rates can affect future repayments.
However, the EMI is only one part of the cost of home ownership. Buyers should also account for taxes, registration, maintenance, insurance and other property-related expenses. Using a mortgage calculator alongside a complete household budget can provide a more realistic picture of the financial commitment involved in purchasing a home.