Yes, dialysis is generally covered by comprehensive health insurance policies in India when it is medically necessary and satisfies the policy conditions. Dialysis is commonly treated as a day-care procedure, which means the patient does not have to remain hospitalized for 24 hours for the treatment to qualify. HDFC ERGO, for example, specifically lists dialysis among treatments that can fall under day-care coverage.
However, coverage is not unlimited. Pre-existing kidney disease, waiting periods, available sum insured, co-payment, sub-limits and the place where dialysis is performed can all affect how much the insurer actually pays.
Why Is Dialysis Covered Even Without 24-Hour Hospitalization?
Traditional health insurance was strongly associated with hospitalization lasting at least 24 hours. Modern medical treatment has changed that.
Many procedures that once required prolonged hospital admission can now be completed within a few hours. Health insurers therefore provide day-care treatment coverage for eligible procedures.
Dialysis is one of the clearest examples.
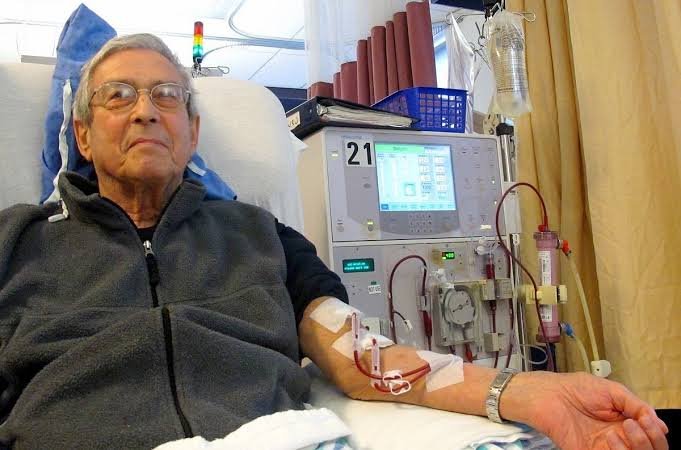
A patient may enter a hospital or dialysis centre, undergo treatment for several hours and return home the same day. HDFC ERGO specifically identifies dialysis, chemotherapy and certain eye surgeries as examples of day-care treatments that may require less than 24 hours at a hospital or day-care centre.
So you should not assume:
“I was not hospitalized overnight, therefore insurance will not pay.”
If your policy covers dialysis as an eligible day-care procedure, an overnight stay is generally unnecessary.
What Dialysis Expenses Can Health Insurance Cover?
The exact expenses depend on the policy, but eligible dialysis treatment can potentially include expenses connected with the medically required session.
Depending on the plan, this may include:
- Dialysis procedure charges
- Day-care facility charges
- Doctor’s fees
- Certain medicines used during treatment
- Diagnostic investigations
- Eligible hospital charges
- Treatment for complications requiring hospitalization
Some policies designed for people with kidney-related conditions may also offer broader benefits. Care Health Insurance, for example, describes dialysis coverage for kidney failure as part of health insurance for kidney patients, subject to the policy terms.
The key words are “subject to policy terms.”
Having a ₹10 lakh sum insured does not necessarily mean every dialysis-related expense worth ₹10 lakh will automatically be reimbursed.
What If Kidney Disease Is Diagnosed After Buying Insurance?
This is usually the simpler insurance situation.
Suppose you purchased health insurance while you did not have diagnosed chronic kidney disease. Several years later, kidney failure develops and your doctor recommends dialysis.
If the policy remains active and the treatment is covered, eligible dialysis expenses can generally be claimed subject to its terms, exclusions and available sum insured.
This is one reason continuous health insurance can become extremely valuable with chronic diseases.
A medical condition requiring repeated treatment can cost much more over several years than a single hospitalization.
What If You Were Already a Kidney Patient?
This is where coverage can become more complicated.
If chronic kidney disease was already diagnosed—or relevant treatment or medical advice had been received—before purchasing the health policy, the condition may be treated as a pre-existing disease.
The insurer may then apply the pre-existing disease provisions and waiting period contained in the policy.
HDFC ERGO’s guidance for people with kidney disease specifically notes that plans may cover pre-existing conditions but that waiting periods, limitations or exclusions relating to existing kidney disease must be checked carefully.
Most importantly, never hide kidney disease, abnormal kidney reports or existing dialysis while buying insurance.
Correct medical disclosure is essential. A policy bought by withholding significant medical information can create serious difficulty when a large claim is later submitted.
Can You Buy Insurance After Dialysis Has Already Started?
You may be able to apply for health insurance, but that does not mean your ongoing dialysis will immediately become covered.
Someone already receiving regular dialysis represents a significantly different insurance risk from a healthy applicant.
Depending on the insurer and product, the proposal may:
- Be accepted with specific terms
- Carry a waiting period
- Have special limits or co-payment
- Be offered under a specialised policy
- Be subject to medical underwriting
- Not provide immediate cover for existing treatment
Some products are specifically designed for people with pre-existing conditions. Care Health Insurance, for example, currently offers a product where the stated pre-existing disease waiting period is 24 months, subject to the plan’s conditions.
Therefore, buying insurance only after dialysis becomes necessary may not solve the immediate financial problem.
Is Every Dialysis Session Covered?
Not necessarily.
This is particularly important because dialysis is a recurring treatment rather than a one-time procedure.
Some policies may cover eligible dialysis sessions from the overall sum insured. Others may contain specific limits on:
- Amount payable per session
- Number of sessions
- Annual dialysis benefit
- Total benefit period
- Type of dialysis
- Approved hospital or centre
ICICI Lombard, for example, notes in information on dialysis and pre-existing disease cover that certain policies may specify an amount for each dialysis sitting or limit the number of sessions covered.
Therefore, don’t simply ask the insurer:
“Is dialysis covered?”
Ask:
“How much will my policy pay per dialysis session, and is there any annual or session limit?”
That is a much more useful question.
Is Dialysis at a Standalone Centre Covered?
Possibly, but check the definition of an eligible day-care centre in your policy.
A dialysis facility may operate inside a large hospital or as a specialised standalone centre.
Health insurance policies generally specify conditions that a day-care centre or medical facility must satisfy. Older IRDAI-hosted policy wordings, for example, define day-care centres as qualifying medical establishments or medical setups within hospitals that meet specified requirements.
Before beginning repeated sessions, check whether your chosen dialysis centre is acceptable to the insurer and whether cashless treatment is available there.
This can save considerable paperwork when treatment is required several times each week.
Is Home Dialysis Covered?
Do not assume it is.
Some patients use treatments such as peritoneal dialysis or other forms of dialysis that can be managed partly at home.
A standard policy’s day-care benefit may be designed primarily around treatment received at a hospital or recognised day-care centre.
Home treatment can involve:
- Dialysis supplies
- Consumables
- Equipment
- Medicines
- Nursing assistance
- Regular medical monitoring
Whether these expenses are covered depends heavily on the individual policy.
Some insurance products may provide broader dialysis or domiciliary benefits, while others may not cover routine home-based supplies.
If home dialysis is being considered, obtain written clarification from the insurer before assuming that the same benefits available for hospital dialysis will apply.
What About Kidney Transplant?
Dialysis and kidney transplant are different treatments, although both may be required in advanced kidney disease.
A comprehensive health insurance policy may cover eligible kidney-transplant hospitalization subject to its conditions, waiting periods and sum insured.
However, transplant claims have additional issues such as:
- Donor-related hospitalization expenses
- Organ harvesting costs
- Recipient surgery
- Post-transplant treatment
- Anti-rejection medicines
- Follow-up expenses
Not every policy covers every donor-related expense.
If a kidney transplant is being planned, check the organ donor benefit separately rather than assuming dialysis coverage automatically means every transplant expense is included.
Regular Health Insurance vs Critical Illness Insurance
This distinction is also important.
Ordinary health insurance generally works on an indemnity basis. It pays admissible medical expenses up to the applicable coverage limit.
Critical illness insurance works differently.
If the insured develops a specified critical illness meeting the policy definition, the insurer may pay a fixed lump-sum benefit.
Some critical illness policies include kidney failure requiring regular dialysis as a covered condition.
HDFC ERGO, for example, describes critical illness insurance for kidney failure as providing a lump-sum benefit that may be used for dialysis, transplant treatment and other expenses after a qualifying diagnosis.
The lump sum can be useful for expenses that ordinary hospitalization insurance may not fully cover, including income loss and other household costs.
Why Can You Still Have Out-of-Pocket Expenses?
- Even when dialysis is covered, the insurer may not pay the entire amount billed.
- Your personal contribution can arise because of:
- Co-payment: You pay a specified percentage of the admissible expense.
- Deductible: You bear a predetermined amount before insurance begins paying.
- Sub-limit: The policy restricts the amount available for dialysis.
- Non-payable expenses: Certain medicines, consumables or miscellaneous charges may not qualify.
- Exhausted sum insured: Frequent dialysis and other hospitalizations may eventually consume the available annual cover.
For a chronic condition, these differences matter considerably because even a modest amount paid personally during every session can become substantial over a year.
What Should You Check Before Starting Dialysis?
Before beginning regular treatment, ask the insurer or TPA:
- Is dialysis covered as day-care treatment?
- Is there any limit per sitting or per year?
- Does my pre-existing disease waiting period apply?
- Is my dialysis centre in the cashless network?
- Are medicines and investigations covered?
- Is home or peritoneal dialysis included?
- Is there a co-payment or deductible?
- How much sum insured is currently available?
Would a planned cashless authorisation cover multiple sessions, or is separate approval required?
Knowing these answers before treatment begins can prevent repeated claim problems.
The Bottom Line
Yes, dialysis is generally covered by health insurance in India when medically necessary and admissible under the policy. It is commonly treated as a day-care procedure, so a patient normally does not need to stay in hospital for 24 hours simply to qualify for coverage.
However, dialysis is a recurring treatment, which makes the details especially important.
If kidney disease existed before the policy began, pre-existing disease conditions and waiting periods may apply. Policies may also impose limits on individual sessions, the number of treatments, or the total amount payable.
Therefore, anyone facing long-term dialysis should check not only whether the word “dialysis” appears under coverage but also the actual financial limit, network-centre rules, waiting period and remaining sum insured.
For chronic kidney disease, those details can make the difference between having insurance on paper and having insurance that genuinely helps with repeated treatment.
FAQs
Q1. Is dialysis covered under a family floater health insurance policy?
It can be. If dialysis is an admissible day-care treatment under the family floater, eligible expenses can be paid from the shared sum insured. Remember that repeated dialysis claims can reduce the amount available to other family members during the same policy year.
Q2. Can I get cashless dialysis every week?
Possibly, if your policy covers dialysis and the treatment is taken at an eligible network facility. Since repeated sessions are required, ask the insurer or TPA whether one authorisation can cover a treatment schedule or whether separate approvals are needed.
Q3. Does health insurance cover dialysis caused by diabetes?
It can, but if diabetes or diabetic kidney disease existed before the policy began, pre-existing disease provisions may apply. The policy’s waiting period and the medical history disclosed when buying insurance will therefore be important.
Q4. Will critical illness insurance pay for every dialysis session?
Usually, critical illness insurance does not work by reimbursing each individual dialysis bill. If kidney failure requiring regular dialysis meets the policy’s specified critical illness definition, an eligible plan may instead pay a fixed lump sum. Regular health insurance and critical illness insurance therefore serve different purposes.