Property can be used for borrowing in two very different ways. Someone planning to purchase a ₹60 lakh apartment may take a home loan to finance the purchase. Another person may already own a property worth ₹60 lakh but need money for business expansion, education or another major requirement. In that case, the property may be mortgaged to raise funds.
This is the basic difference between a home loan and a mortgage loan.
In India, the term “mortgage loan” is commonly used in retail lending for a Loan Against Property (LAP)—a loan raised by mortgaging an existing property for purposes other than purchasing or constructing that same home. RBI’s housing-finance framework similarly distinguishes housing finance from loans given against mortgaged property for other purposes.
Both loans are secured by property, but their purpose, cost, loan amount and repayment structure can be quite different. Understanding those differences makes it easier to choose the right option.
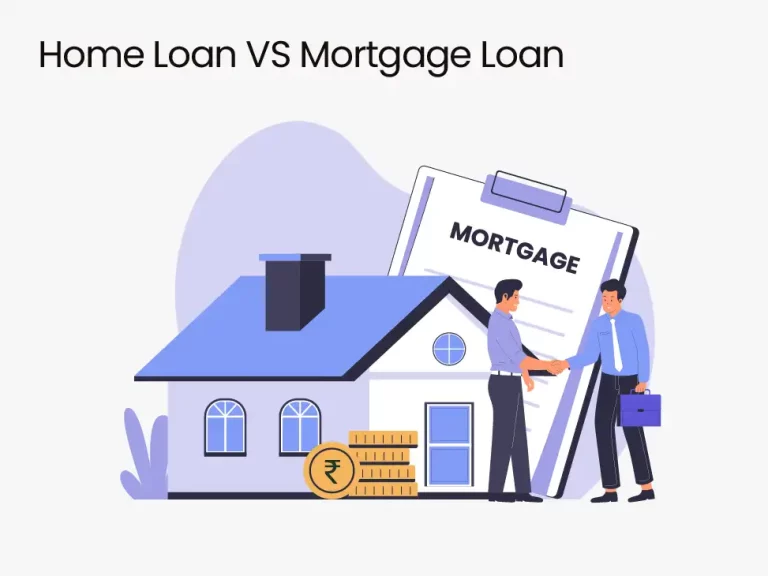
What Is a Home Loan?
A home loan is financing taken specifically for an eligible housing purpose.
It may be used to purchase a new or resale residential property, construct a house, or in certain products, renovate or improve an existing home. RBI describes housing loans as loans used for the acquisition, construction, repairs or upgrading of residential property.
The property being purchased or constructed normally becomes the primary security for the lender.
Because the loan has a clearly defined housing purpose, the lender generally disburses the money according to the property transaction or construction schedule rather than providing unrestricted cash to the borrower.
What Is a Mortgage Loan?
In the common Indian lending context, a mortgage loan or Loan Against Property involves pledging an already owned residential, commercial or other eligible property to obtain money.
The borrower normally continues to own and use the property while repaying the loan.
Unlike a home loan, the money is not necessarily being borrowed to purchase the mortgaged property. Depending on lender rules, it may be used for business requirements, education, medical expenses or other approved purposes.
That flexibility is one of the biggest attractions of mortgage loans.
1. Purpose of the Loan
Purpose creates the most important difference.
A home loan has a specific housing purpose. If you want to purchase a flat, build a house or finance another eligible residential requirement, a home loan is generally the appropriate product.
A mortgage loan offers broader usage because money is raised against property already owned.
For example, suppose a business owner owns a house but requires ₹20 lakh to purchase machinery. A normal home loan cannot simply be taken for that business requirement. A Loan Against Property may be considered instead.
Therefore, home loans finance the property itself, while mortgage loans unlock money from property that the borrower already owns.
2. Interest Rates
Home loans generally have an advantage when it comes to borrowing cost.
Because housing loans have a defined end use and finance the creation or purchase of a residential asset, lenders may offer them at more competitive rates than Loan Against Property products.
Mortgage loans can carry higher rates because the money may be used for a wider range of purposes.
The actual difference varies by lender, borrower profile, property, loan amount and market conditions.
For a long-term loan involving a substantial amount, even a relatively small interest-rate difference can significantly affect total repayment.
3. Loan Amount
Both products can provide substantial financing, but the method of calculating the available amount differs.
For a home loan, lenders consider the property’s cost or valuation, required borrower contribution and the applicant’s repayment capacity. RBI rules and lender policies also govern how much of the property value may be financed.
For a mortgage loan, the lender values the property already owned and generally offers only a percentage of that assessed value.
Owning a property worth ₹1 crore therefore does not mean the owner can automatically borrow ₹1 crore against it.
Income, existing EMIs, age, credit profile and property quality can further influence the sanctioned amount.
4. Repayment Tenure
Home loans are designed for long-term property ownership and can therefore offer lengthy repayment periods.
This helps spread a large property purchase over manageable monthly EMIs.
Mortgage loans may also provide relatively long repayment periods, but their maximum tenure is often shorter than that available for home loans, depending on the lender.
A shorter tenure means the debt may finish earlier, but it can also result in a substantially higher EMI.
Borrowers should compare both the monthly repayment and the total interest payable over the complete tenure.
5. Property Ownership at the Time of Application
With a home loan, the borrower does not necessarily own the property before applying. The loan itself helps finance its purchase or construction.
With a mortgage loan, the borrower generally already owns an eligible property that can be pledged.
This makes the two products suitable for completely different financial situations.
A first-time buyer searching for a home normally needs a home loan. A property owner seeking liquidity from an existing asset may consider a mortgage loan.
6. Flexibility in Using the Money
Mortgage loans have a clear advantage in flexibility.
Home-loan funds must be used for the approved housing purpose.
Money raised through Loan Against Property can generally be used for a wider range of permitted requirements according to the lender’s conditions.
For a business owner who needs substantial capital but does not want to sell property, this can be extremely useful.
However, flexibility should not encourage unnecessary borrowing. Mortgaging valuable property to finance routine spending or speculative investments can create serious financial risk.
7. Documentation and Property Checks
Both loans involve property verification.
For a home loan, the lender checks the property being purchased, ownership documents, title and other required legal and technical details. RBI advises borrowers to ensure that the property’s title is clear and free from problematic encumbrances.
Mortgage loans require similar attention because an existing property is being accepted as collateral.
The lender may conduct legal verification and an independent valuation before deciding how much it is willing to lend.
Complicated ownership, disputed title or incomplete documentation can delay either type of loan.
8. Risk to the Property
Both home loans and mortgage loans are secured borrowing.
If repayment problems become serious and remain unresolved, the mortgaged property can ultimately become subject to recovery proceedings according to the agreement and applicable law.
However, the practical risk can feel different.
With a home loan, the property was purchased using the loan itself. With a Loan Against Property, someone may be pledging a valuable home or commercial property they already owned before borrowing.
That makes it especially important not to mortgage an essential family asset for an uncertain or highly speculative purpose.
Which Is Better?
A home loan is usually better when the objective is buying, constructing or financing an eligible residential property. Its dedicated housing purpose, potentially lower interest rate and longer repayment tenure make it more appropriate for home ownership.
A mortgage loan is better when you already own property and need a substantial amount for another approved purpose. It provides flexibility without requiring the property to be sold.
The two products therefore are not direct substitutes in most situations.
If you want a new house, consider a home loan. If you already have property and want to unlock some of its value, a mortgage loan may be more suitable.
Frequently Asked Questions
Q1. Can I take a mortgage loan on a commercial property?
Possibly. Many lenders consider eligible commercial properties for Loan Against Property, subject to ownership, location, valuation, legal title and their individual lending policies.
Q2. Can I sell a property while a mortgage loan is still running?
A mortgaged property generally cannot be freely sold without dealing with the lender’s outstanding charge. A sale may still be possible through an agreed process in which the outstanding loan is settled and the lender releases its security.
Q3. Can a jointly owned property be used for a mortgage loan?
It may be possible, but the lender will normally require the consent and participation of the relevant co-owners. Additional documentation or co-applicant requirements can apply.
Q4. Does the lender become the owner of my property after I take a mortgage loan?
No. Creating a mortgage does not normally transfer everyday ownership and possession to the lender. The borrower continues to own and use the property while complying with the loan terms. The mortgage gives the lender security against the debt.